Smith Manoeuvre
The tax side of your Smith Manoeuvre.
Most Smith Manoeuvre illustrations show two lines: your mortgage coming down and your investments going up. My team at Senova works on the third line, the one that decides whether the strategy was worth it: what you and your family keep after tax.
Is it for you?
The Smith Manoeuvre turns your mortgage into investment debt over time. Each time a payment brings the mortgage down, you borrow the same amount back on a line of credit and invest it. Interest on that line can be deductible, as long as each borrowed dollar is traced to something that earns income.
It can suit you if
- you have, or can get, a readvanceable mortgage;
- your income is steady and you're investing for the long term;
- you'll keep simple monthly records;
- you're already running it and want it checked.
It's probably not for you if
- borrowing to invest would keep you up at night;
- a market fall would force you to sell;
- your income isn't steady enough to carry the interest.
Whether it fits depends on your income, your other savings options and how much risk you can carry. We test it against your RRSP, TFSA and other choices before you commit to it.
What we do
The deduction depends on things your lender doesn't track: what each borrowed dollar paid for, which spouse should claim it, and what changes when you add a suite, refinance or sell. That's the part we take on, alongside your mortgage broker and financial advisor.
- Before you begin. A one-time review of your setup, so you know what's deductible and who should claim it.
- Every year. Your return filed with each borrowed dollar traced to something that earns income: investments, a rental or your business. Once the setup is clean, it's priced like any other return.
- If it has drifted. The records rebuilt month by month, and the plan put back on track.
Decisions made at setup are the hardest to change later, so it pays to bring us in before the first draw.
Free Health Check
How healthy is the tax side of your setup?
Twelve questions: who borrows, who owns, how the money moves and what gets claimed. You'll get a health score out of 100, a colour for every answer, and a short list of what to sort out.
- For planning or runningAnswer for the setup you have, or the one you're planning. Not sure is always an option.
- Green, amber or redAny red, or three ambers, takes you out of the green. Each one comes with why it matters and what to do. Rentals, suites and debt swaps show as notes, not problems.
- On paper tooThere's a one-page PDF of the same questions.
What it costs
Fixed fees, agreed with you in writing before we start. We don't pay or take referral fees, and we don't arrange mortgages or sell investments.
Smith Manoeuvre Setup Consult
$750 standard, or $1,250 complex. Plus applicable sales taxes.
A one-time review of who borrows, who owns, how the money moves, what gets claimed and the exit. You get a written memo you keep, and your broker gets a copy if you agree.
The $1,250 fee applies if any of these are part of your setup:
- a rental property, or a cash flow dam;
- a suite or other rented part of the home;
- more than one lender or readvanceable line;
- a debt swap of investments you already own;
- spouses borrowing, owning or investing unequally;
- a strategy that's already running.
Business owners: if you later bring us your corporation, the setup fee is credited in full against your first year.
Tracing Rebuild
$595 standard, or $950 complex. Plus applicable sales taxes.
For a line that's paid for something other than investing, or a trail that needs rebuilding. We work out the deductible balance and interest month by month, and recommend the correction.
The standard fee covers one line and up to three tax years. The $950 fee covers up to six tax years, and applies if any of these are part of the setup:
- two people's shares to separate;
- a rental, a suite or a cash flow dam;
- more than one lender, or a refinance that combined balances.
Amending past returns, and anything held through a corporation or trust, is quoted separately.
About Sayed
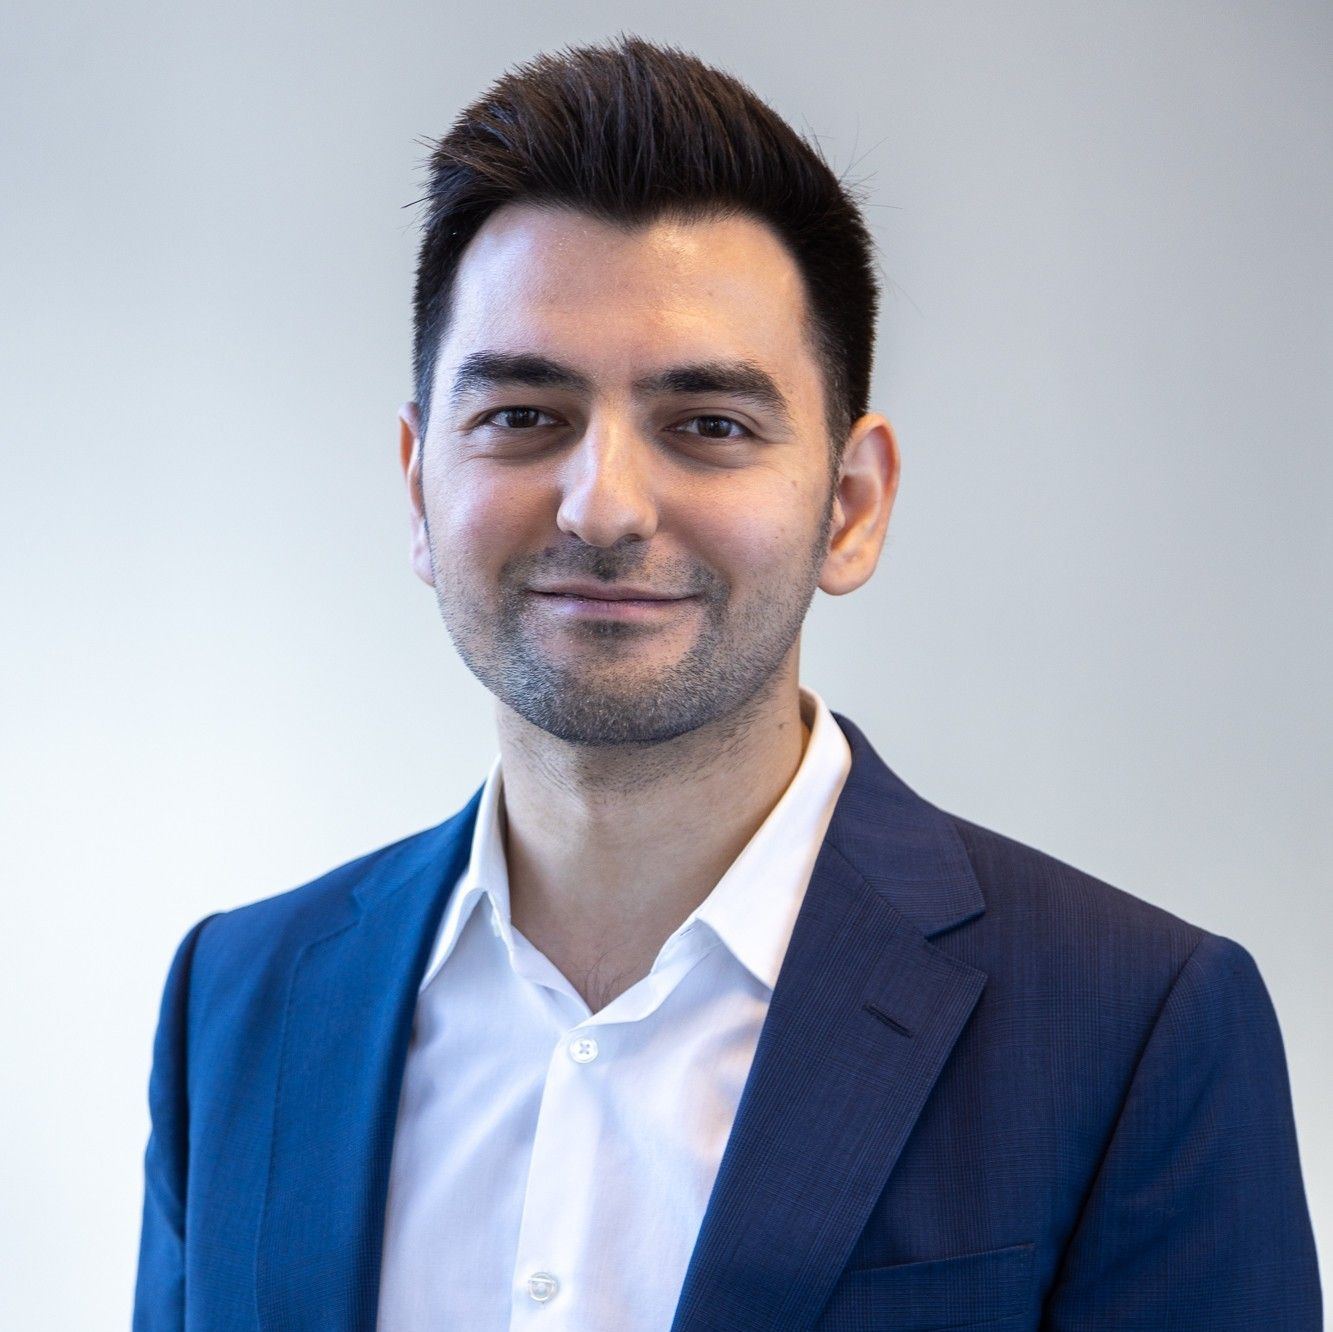
Sayed Hussaini, CPA · Smith Manoeuvre Certified Professional™
Sayed is the founder of Senova CPA in Vancouver. He works with families and business owners on lifetime tax planning, including the tax side of the Smith Manoeuvre: tracing, rental and suite allocations, couples and corporations. The strategy gets weighed against your RRSP, TFSA, corporation and eventual sale, not looked at on its own.
For mortgage brokers and advisers
You set up the borrowing. We look after the tax side, and your client stays your client.
- Send your client the Health Check. This page, or the one-page PDF, before or after implementation.
- They see where they stand. A health score and a short list of what to sort out. Their answers stay in their browser unless they choose to send them to us.
- If they'd like a CPA to look at it, they bring their results to us. We agree the scope and fee with them first. With their consent, you get a copy of what we find.
We don't pay or take referral fees, in either direction. We can talk through how the rules work in general; advice on a particular client's file starts once they've engaged us. Questions: info@senovacpa.ca or 604-771-8497.
Questions
We're a couple. Who should claim the interest?
Generally the spouse who used the borrowed money to invest, in investments in their own name. CRA has said both of you can be on the line, with the home as security, and the owner can still deduct the interest. Keep it clean: the owner makes the draws, and the other spouse's money never pays the interest.
We're a few years in and the line got mixed up. Can it be fixed?
The deductible part can be worked out month by month from the statements, and the setup corrected from here on. Paying a personal draw back doesn't reset the split on its own, so it's worth doing properly. That's the Tracing Rebuild.
What happens when we sell a rental bought with the line?
The interest on that part of the line generally stops being deductible unless the money goes back into something that earns income. The rule that protects the deduction after a loss on investments doesn't cover real estate, so plan the sale before you list.
Does a return of capital always reduce the deductible loan?
Only if it's used for something other than investing. CRA's view is that the interest stays deductible on a return of capital that's reinvested. Putting it back on the line simply pays that part down.
How is the health score worked out?
Each green answer and each note counts fully, each amber counts half and each red counts nothing. The score is then held inside its colour's band, so the number always matches the colour: any red keeps it at 59 or below, and three or more ambers keep it between 60 and 84. 85 and above is the green.
Is a high score a sign-off on my setup?
No. The check scores your answers, not your statements. It points to what's worth looking at. Only a review of the actual accounts and returns can tell you what's deductible.
What if we've moved, separated or lost a spouse?
The deduction follows how the borrowed money was used, not the house or the lender. Any of these changes who can claim what, so it's worth a conversation before the next return.
Is there anything else to watch on a large line?
Yes. On a large line, the alternative minimum tax counts only half of the interest. Ask whoever prepares your return whether that applies to you.
Where are your clients?
We're in Vancouver and work with clients across Canada outside Quebec.
What happens to my Health Check answers?
They stay in this browser tab. Nothing is sent unless you choose to bring your results into an inquiry and submit it. Privacy details.
Sources
Rules reviewed October 12, 2026.
- Income Tax Act, s.20(1)(c), (d) and 20(3): interest and borrowed money
- Income Tax Act, s.18(3.1) and 18(11): construction-period interest and registered plans
- Income Tax Act, s.20.1: borrowed money and lost sources of income
- Income Tax Act, s.45: change in use of property
- Income Tax Act, s.54: superficial loss
- Income Tax Act, s.74.1: attribution between spouses
- Income Tax Act, s.74.5: loans and guarantees between spouses
- Income Tax Act, s.127.52: alternative minimum tax
- CRA Income Tax Folio S3-F6-C1, Interest Deductibility
- CRA Income Tax Folio S1-F3-C2, Principal Residence
- CRA: Line 22100, carrying charges and interest expenses
- CRA Guide T4036, Rental Income
- CRA technical interpretation 2009-0317041E5, July 20, 2009: spousal attribution and a joint line of credit
Want a CPA to look at your setup?
Tell us where you are with the strategy. We'll agree the scope and fee with you before any work starts.